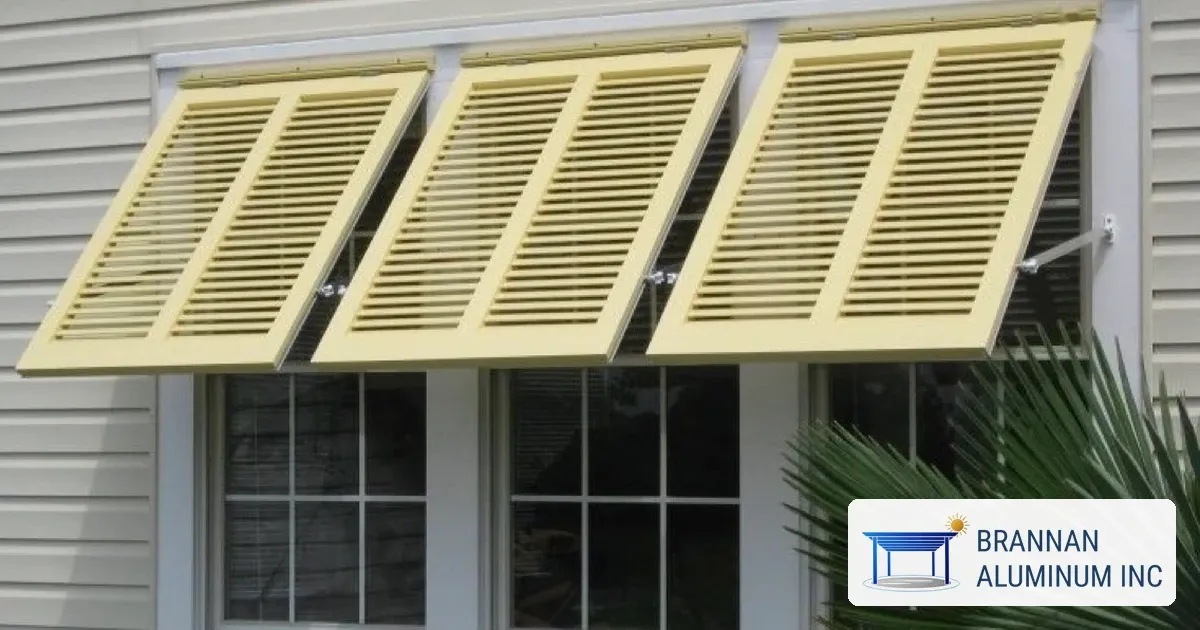
Does Hurricane Protection Lower Your Florida Home Insurance? What the Law Says and What to Ask
Does Hurricane Protection Lower Your Florida Home Insurance? What the Law Says and What to Ask
Florida law requires home insurers to build discounts for hurricane protection into their rates, and opening protection is one of the features the statute names. What the law does not do is set the size of the discount. That depends on your insurer, your policy and what an inspector verifies on your home.
This guide explains what the statute requires, how the state's wind mitigation form works and who can sign it, and what to ask your agent before you spend money on shutters, panels or impact windows.
Quick answer
Does hurricane protection lower my homeowners insurance in Florida?
It can, but the law does not set the amount. Under Florida Statute 627.0629, a residential property insurer's rate filing must include actuarially reasonable discounts, credits or other rate differentials, or lower deductibles, for homes with fixtures or construction techniques shown to reduce windstorm loss, and the statute names opening protection among them. Insurers must also post information about their hurricane mitigation discounts on their websites. To claim a discount, a policyholder submits the state's Uniform Mitigation Verification Inspection Form, signed by an authorized mitigation inspector, and the insurer must accept a valid form under Florida Statute 627.711. The form's opening protection section gives its highest level of credit to homes where all openings are large-missile-impact rated or protected, and that includes entry and garage doors, not only windows. The size of any discount varies by insurer, policy and home, so ask your agent before assuming a number.
What does Florida law say about insurance discounts for hurricane protection?
Florida Statute 627.0629 states the Legislature's intent that insurers provide savings to consumers who install windstorm damage mitigation techniques. A rate filing for residential property insurance must include actuarially reasonable discounts, credits or other rate differentials, or appropriate reductions in deductibles, for properties with fixtures or construction techniques demonstrated to reduce windstorm loss.
The statute says those fixtures and techniques must include, but are not limited to, wind uplift prevention, roof strength, roof covering performance, roof-to-wall strength, wall-to-floor-to-foundation strength, opening protection, and window, door and skylight strength. Credits for features that meet only the minimum requirements of the Florida Building Code must also be included in the rate filing.
Two provisions help homeowners find the numbers. Since October 1, 2023, each insurer must publish information about its hurricane mitigation discounts on its website, on or linked from the home page or the primary page for property policyholders. And on or before January 1, 2025, and every five years after, the Office of Insurance Regulation must reevaluate which fixtures and techniques reduce windstorm loss and the discounts that reflect their full actuarial value.
What is the wind mitigation form, and who can sign it?
Florida Statute 627.711 directs the Financial Services Commission to develop a uniform mitigation verification inspection form that all insurers use when policyholders submit it to factor in wind insurance discounts. The form is known as OIR-B1-1802. An insurer must accept as valid a form signed by an authorized mitigation inspector.
The statute names licensed home inspectors who have completed at least three hours of approved hurricane mitigation training and passed a proficiency exam, and it lists other qualified categories as well. An insurer may have a form independently verified, and may waive that for inspectors or companies with a quality assurance program it has approved.
What does the form record about opening protection?
The form's opening protection section covers exterior doors, garage doors, windows, glass blocks and skylights. According to the state's My Safe Florida Home program, the highest level of credit, called A.1, applies when all openings are large-missile-impact rated or protected by products that qualify as such. The next levels turn on doors. Level A.2 applies when all glazed openings are impact rated or protected and every solid entry door and the garage door are verified as wind and pressure rated. Level A.3 applies when the glazed openings are covered but the solid doors and garage door cannot be identified as rated.
The practical point is that covering the windows is only part of the rating. Entry doors and the garage door are scored too, so a home with protection on every window can still fall short of the top level.
What should you ask your agent before buying hurricane protection?
- Where is the discount information? Ask where the insurer posts its hurricane mitigation discounts, and read the entry for opening protection.
- Which level does the insurer credit? Ask whether entry doors and the garage door must also qualify before you get credit for the windows.
- Who can sign? Ask which inspectors the insurer accepts and whether it reviews forms independently.
- What is the credit for your policy? Ask for the amount in writing before you sign a contract.
- What paperwork should you keep? Keep the product's approval label, receipts and installation documents so an inspector can document what is installed.
What does this guide not settle?
- The size of any discount. It varies by insurer, policy and home. We do not quote a percentage because the statute does not set one.
- The current wording of the form's levels. We took the level descriptions from the My Safe Florida Home program's explanation rather than from the form itself, so check the current form.
- Whether a particular product qualifies. That depends on the product's approval and on what the inspector can verify.
- Rules for Citizens Property Insurance Corporation or any single insurer. We have not reviewed them.
- Advice about your policy. This is general information, and we are not insurance agents or lawyers.
What should you do this week?
- Find your insurer's hurricane mitigation discount page.
- List which openings on your home are protected, including the garage door and entry doors.
- Ask your agent the questions above.
- If you plan to buy protection, get each product's Florida Product Approval number before you sign.
Sources
- The Florida Senate. Florida Statutes §627.0629, Residential property insurance; rate filings. 2026. flsenate.gov
- The Florida Senate. Florida Statutes §627.711, Notice of premium discounts for hurricane loss mitigation; uniform mitigation verification inspection form. 2024. flsenate.gov
- My Safe Florida Home. Understanding Opening Protection Ratings on the Uniform Mitigation Verification Inspection Form "1802". support.mysafeflhome.com
